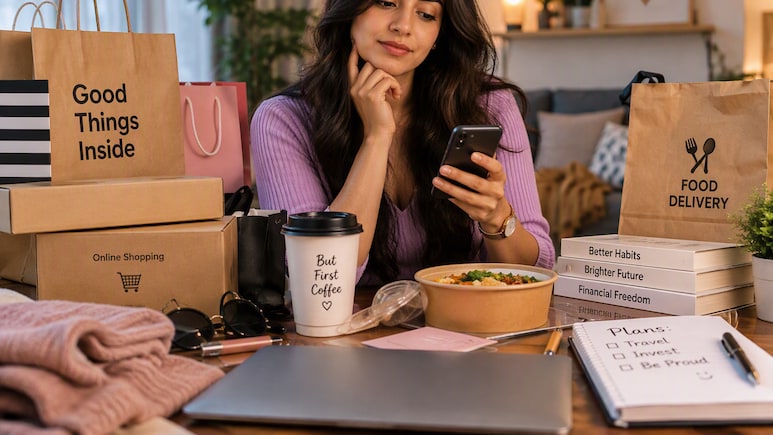
Most of us do not think twice before spending a few hundred rupees here and there. A coffee on the way to work, an online shopping deal that seems too good to miss, or a late-night food delivery can feel like small rewards in the middle of a busy week. Individually, these purchases rarely seem significant. However, when repeated regularly, they can quietly add up to a surprisingly large amount over time. Sometimes, a single monthly SIP costs less than the habits we barely notice, making everyday spending worth a closer look today.
Small purchases often feel insignificant until you see how regularly they appear in your monthly spending.
Photo Credit: Ai generated
This is not about giving up life's pleasures or feeling guilty every time you spend money. In fact, small indulgences are often what make busy days more enjoyable. The real question is whether some habits have become so routine that we no longer notice their true cost. Looking closely at everyday spending can reveal opportunities to create a better balance between enjoying the present and preparing for the future. You may be surprised to discover that a few small adjustments could cost less than you think and potentially achieve much more.
The Daily Coffee That Is Not Really About Coffee
For many professionals, the day starts with a café visit. It is a little ritual that offers comfort before meetings, deadlines and long commutes. A coffee priced at ₹200 may not seem expensive. In fact, it often feels like a well-deserved treat. The interesting part comes when that coffee becomes a daily habit. At five coffees a week, the monthly spend can easily cross ₹4,000. Suddenly, that harmless morning purchase looks very different. This does not mean giving up coffee altogether. Rather, it highlights how recurring expenses often hide in plain sight. Many people are surprised to learn that a modest SIP can begin with considerably less than what they spend on their favourite caffeine fix each month. Sometimes it is not about cutting the coffee. It is about recognising the trade-offs being made without even realising it.
Also Read: What Is The Difference Between Saving And Investing? Can Either Beat Inflation?
The Food Delivery Habit That Feels Convenient
There are days when cooking feels impossible. After a long day at work or a hectic weekend, ordering dinner can feel like the easiest option. The problem is that convenience tends to become a habit very quickly. What starts as an occasional treat can quietly become a 3-4 times per week routine.
A couple of food delivery orders each week may not seem excessive on their own. Yet by the end of the month, the total can be surprisingly high. Service charges, delivery fees, platform fees and taxes often increase the final amount far beyond the menu price. Looking at the monthly total rather than individual orders can be eye-opening. It reminds us that we often focus on the cost of one transaction while overlooking the cumulative impact of dozens of small decisions.
Online deals can make spending feel effortless and easy to justify.
Photo Credit: Ai generated
The Online Cart That Is Always Waiting
One of the easiest ways to spend money today is through online shopping. There is always a sale, a limited-time offer or a product that claims to solve a problem you did not know you had. Because purchases happen with just a few taps, spending rarely feels as tangible as it once did. Many shoppers have experienced the excitement of adding something to their cart because it is heavily discounted.
The logic feels sound at the time. After all, saving 50% appears to be a good financial decision. Yet the reality is that spending money on something unnecessary is still spending money. A few impulse purchases every month can quietly cost more than a regular SIP contribution. The challenge is not resisting every purchase. It is learning to pause and ask a simple question: would I still want this item if it were not on sale?
Subscription Creep Is More Expensive Than It Looks
Most households today have at least a few subscriptions. Streaming services, fitness apps, music platforms, cloud storage and premium memberships have become part of modern life. Individually, each subscription feels affordable. A few hundred rupees here and there rarely raise concern. The issue arises when subscriptions accumulate. Many people continue paying for services they barely use simply because the renewal happens automatically.
Also Read: Financial Independence For Women: A Simple Guide To Starting Your First SIP
A monthly audit of subscriptions can be surprisingly revealing. It is not uncommon to discover multiple overlapping services or memberships that have not been used in months. What makes subscription spending particularly tricky is that it becomes invisible. Unlike a large shopping purchase, it blends quietly into monthly expenses. Yet the annual cost can be significant enough to rival meaningful savings or investment goals.
Small Upgrades That Become Lifestyle Habits
Modern life constantly encourages upgrades. Premium seating, faster delivery, luxury packaging, paid convenience options and exclusive memberships are everywhere. None of them appear expensive individually. The temptation often comes from the idea that it is "just a little extra." This mindset is exactly why lifestyle inflation can be difficult to notice. As incomes grow, spending patterns often shift alongside them.
The occasional premium upgrade becomes the default choice. Over time, these small additions create a higher baseline for daily spending. There is nothing wrong with enjoying better experiences, but it is worth asking whether every upgrade genuinely adds value. Sometimes the money spent chasing convenience could be working towards something more meaningful in the background.
Financial planning is not about cutting every pleasure but spending with intention.
Photo Credit: Ai generated
Why This Is Not Really About Spending Less
Conversations about money often create the impression that every enjoyable expense needs to be eliminated. In reality, the goal is not to stop spending. Life is meant to be enjoyed, and financial planning should support that. The more useful approach is intentional spending. When people understand where their money goes, they can decide what genuinely matters to them. Some may happily keep their daily coffee while reducing impulse shopping.
Others might choose fewer food deliveries in exchange for greater flexibility later. Financial habits become more sustainable when they reflect personal priorities rather than strict rules. What often makes the biggest difference is awareness. Many of the expenses that quietly affect our finances are not large purchases but small recurring behaviours that have become automatic.
The Underrated Benefit Of Starting Small
One reason people delay investing is the belief that they need a large amount of money to begin. Yet many financial habits start with surprisingly small amounts. A monthly SIP is a good example of this. It is not about making dramatic sacrifices or overhauling your lifestyle overnight. Instead, it is about redirecting a small portion of money that may already be leaving your account each month. The amount matters less than the consistency.
Small financial habits can become meaningful long-term decisions.
Photo Credit: Ai generated
Just as daily spending habits become routines, investing habits can too. Today, investment platforms such as Groww have made it easier for beginners to start SIPs, explore mutual funds and manage investments digitally. The platform itself is only a tool. The bigger shift comes from seeing everyday spending differently and recognising that even small amounts can serve a larger purpose when used intentionally.
In Conclusion
Most financial goals are not achieved through one big decision. They are usually shaped by everyday habits repeated over time. A coffee, subscription, food delivery order or impulse purchase might seem insignificant on its own, but small expenses have a surprising way of adding up. This does not mean cutting out everything you enjoy. It simply means paying attention to what becomes automatic. The next time you add something to your cart, it may be worth pausing for a moment. Sometimes the most powerful financial habit is not spending less, but becoming more conscious about where your money goes each day. Try Groww for yourself today.
Frequently Asked Questions (FAQs)
Q1. Are small daily expenses really a problem?
Not necessarily. Small expenses become a concern only when they turn into consistent habits that consume a significant portion of your monthly budget without providing much value in return.
Q2. Should I stop spending on things I enjoy?
No. Financial planning is generally more sustainable when it includes room for enjoyment. The goal is to spend intentionally rather than cut out every pleasure.
Q3. How can I identify wasteful spending habits?
Reviewing bank statements and payment app histories can help reveal recurring expenses. Many people discover patterns they were not fully aware of until they see the monthly totals.
Q4. Can a SIP be started with a small amount?
Yes. Many SIPs allow investors to start with relatively modest monthly contributions, making them accessible for beginners who are building investing habits gradually.
Q5. What is the biggest benefit of tracking small expenses?
Tracking expenses increases awareness. Once you understand where your money is going, it becomes easier to align spending with your personal goals and priorities.
Disclaimer: This article may include references to or features of products and services made available through affiliate marketing campaigns. NDTV Convergence Limited (“NDTV”) strives to maintain editorial independence while participating in such campaigns. NDTV does not assume responsibility for the performance or claims of any featured products or services.
